Monday, December 13, 2010

Guest Post: How To Kick Off Your Job Search

This guest post is contributed by Kate Willson, who writes on the topics of best online colleges. She welcomes your comments at her email: katewillson2@gmail.com.


Whether you’re a recent college graduate or someone who's recently lost his or her job, you know that it's about time to kick off your job search. It's natural to feel a little intimidated nowadays, especially because the job market is so tough and doesn't seem to be getting any better. But don't let that get you down too much. If you can come up with a solid plan, one that works for you, then you'll be able to battle those bad feelings and be confident in your job hunt. Here are a few tips to consider as you kick off your job search.


Make Goals

The first thing you need to do is make a list of goals that you'd like to accomplish with this job search. Do you want to find a job in a different career path? Are you hoping for a job with higher pay? Do you need to get a job that works as a good entry-level position? How long can you afford to go jobless? Do you want to stay where you are or can you move? All of these goals—and more—will dictate how you go about your job search. For example, if you're goal is to find a job within three months, ask yourself how many applications you feel like you need to send out each week in order to make that a reasonable goal.


Establish a Routine

The first key to your job search is making sure you have a routine that you can follow every day. Remaining consistent in your approach to finding a job is one way to make sure you always have some action on your application somewhere out there. The biggest thing to do is get out of bed at a reasonable hour, and work throughout the day as if you were already employed. Split your day into chunks based on your job-hunting goals. For example, devote your morning to searching out new positions. Compile these, put them in a spreadsheet, and then break for lunch. When you come back, work on your existing applications, composing and revising cover letters, tweaking your resume, and following up with your personal and professional references.


Ask for Help

At some point during your job hunt, you will need to ask for help. Talk to your friends who have gone through the process recently and ask for their advice. Contact a career advisor at your former college or university, or if you're too far away from school, then consider talking to a mentor figure who might also be able to help. Don't be afraid to alert your friends and family about your job hunt, as they might be able to help you find leads to check out.


Follow Through

Finally, you must follow through. No amount of planning and scheduling will help you find a job if you cannot follow through on your plans. At the end of every week, you must be able to point to a list of jobs to which you applied. You must be able to show a friend this list and explain what you did in order to send these applications out. You must prepare for an interview, even if you don't have one scheduled. By following through on your promises, you hold yourself accountable for your failures and your successes. After all, the job hunt is for you and no one else.

Friday, December 3, 2010

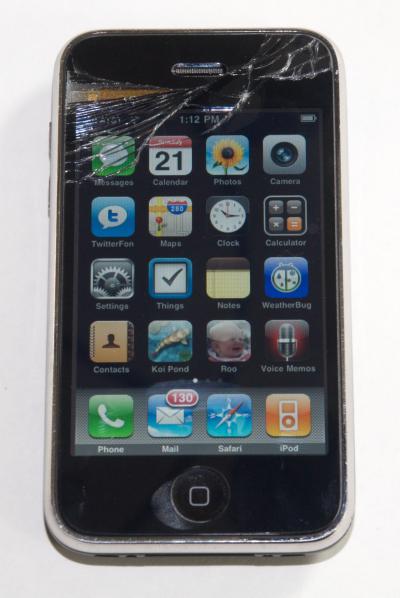
Phone Woes

Image via

Recently while rushing out of the house, I dropped my iPhone (3G) and the screen cracked! This will teach me not to rush out of the door like that anymore...Prior to cracking my phone, it was in excellent condition and I've had no issues with it. I'm so bummed! I had no plans to purchase a new phone in the immediate future, but it looks like I won't have a choice. I'm going to manage with the cracked phone until the holidays are over and see how long I can use the phone with out difficulty with the cracked screen. I'm not sure if iPhone screens are replacable, I guess I'll investigate that too.

Have you had to make any unexpected technology replacement purchases recently?

Tuesday, November 30, 2010

Weekly Money Check-Up

Image via MPP


This week, I decided to participate in My Pretty Pennies Weekly Money Check-Up because after being a bit neglectful of my finances for the last few weeks, it's time to get back on track!

  1. The most I’ve spent this last week was $45 on ingredients for my contribution to Thanksgiving dinner, Spice Cupcakes with White Chocolate Cream Cheese Frosting. I was a little shocked that the ingredients cost so much, but they turned out delicious so I guess the money was worth it.
  2. Today I feel excited about money because it’s a pay week and that's always something to be excited about :- )
  3. Money can’t buy happiness. One free/inexpensive thing I did last week that made me happy was spend time with my family during the Thanksgiving holiday. I didn't get to see some of my hometown friends, but look foward seeing them later in the holiday season.
  4. I will consider this week a success if I complete the first draft of a paper that is due in two weeks and start my Christmas shopping!
  5. My favorite holiday song is 'Carol of the Bells' I haven't yet heard a version of the song I didn't like. I have fond memories of singing the song in my high school choir.

Monday, November 29, 2010

What Did I Purchase on Black Friday and Cyber Monday?

Nothing! I did have some discretionary spending on food and transportation, but I didn't spend any money shopping for myself or anyone else on Black Friday or today, Cyber Monday. I'm sure there are still deals that can be found, but they won't be found by me. My holiday gift list this year is not extensive and I plan to purchase most of my gifts locally and make an effort to buy handmade items (not by me though!) over the next few weeks. If I had to replace technology products that are 'necessities' like my phone or laptop, I may have been tempted to shop, but to be honest, I just wasn't inspired to fight the crowds for a 'deal' this year. I'm embracing the things I love most about the holiday season; spending time with loved ones, reflecting on all of the things I have to be thankful for, helping others in some way (large or small), but I think my wallet will thank me if I don't sucked into the consumerism that the holidays can also bring this year. I've certainly done my fair share of stimulating the economy in 2010 anyway :- )

Did you take advantage of the deals and shop on Black Friday or Cyber Monday?

Wednesday, November 24, 2010

My Favorite Books of 2010

I am the type of person that always has a book in my bag for my daily public transportation commute and I also make good use of my local library. Here are my thoughts on my favorite books of 2010 in no particular order:

  • If You Have to Cry, Go Outside by Kelly Cutrone. I loved the no-nonsense attitude of Kelly Cutrone. I didn't know much about her until I watched her reality show (is it coming back?) on Bravo. This is a great book for a recent college graduate interested in working in the fashion industry or any teen/young female professional that needs inspiration on 'making it'.
  • My Life in France by Julia Child. I was inspired to read this book after seeing the film Julie & Julia earlier this year. I have to say, reading about Julia Child's interesting years living in France with her husband was much better than the film. I admired her tenacity to keep plugging away toward her goal of completing her timeless cookbook despite setbacks. She seems like someone I would have enjoyed sitting down and having a cup of tea with if she were still alive.
  • B*tch is the New Black by Helena Andrews. I loved Helena Andrews sarcastic humor and the way she described her interesting childhood and experiences dating as a young professional black woman in her essays.
  • Cane River by Lalita Tademy. This historical novel based on the real-life occurrences of a woman's family during slavery in Louisiana was a compelling read. The author spent years researching her family to write this fictional version of her family's story.
  • Linchpin: Are You Indispensable? by Seth Godin. If you need a jump start to get your creative initiative going, this is the book to read. I have read a few of Godin's books and this one is my favorite so far. There are so many gems in this book, I think I might actually purchase it so I can reference it later.
  • Girl with the Dragon Tattoo by Stieg Larsson. This fast-paced and slightly disturbing thriller/mystery captivated me from the first page and I couldn't put it down until I finished it. I've already read the Girl Who Played with Fire and just picked up the final book in the trilogy, The Girl Who Kicked the Hornet's Nest. I'm already sad that there will be no more books from Larsson because he died shortly after completing the first three books in what was planned to be an ongoing series according to Wikipedia.
  • Water for Elephants by Sara Gruen. I didn't expect to like this book because (a) I don't really enjoy the circus, seeing animals in captivity makes me sad, (b) I didn't think I'd be able to relate to the protagonist, but I was pleasantly surprised by how much I enjoyed this book and read it pretty quickly. It was surprising that one of the most compelling characters in the novel was not human, and that's all I'll say in case you haven't yet read it.
  • The Millionaire Next Door by Thomas Stanley and William Danko. I'm a little late to the game in reading this book because I have seen so many bloggers reference it over the last few years. Though I personally think the scope of the research of this book is limited, I really liked the major premise of the book; that you don't have to be born with a silver spoon in your mouth to accumulate wealth and that high consumers are not necessarily the rich folks in American society. The data presented in the book did present interesting stories and really made me rethink about how I perceive wealth.
  • I Will Teach You To Be Rich by Ramit Sethi. If you love the tone and content of Ramit Sethi's highly popular blog, than you'll like this book. The advice in the book was presented in a fresh way and I liked the slightly irreverent tone of his writing. I would purchase this book for anyone I know that is a recent college grad just learning to manage their money.
  • The Hunger Games Trilogy by Suzanne Collins. After seeing a few bloggers reference these books, I decided to pick up The Hunger Games from the library. I didn't expect to like them because of the somber and disturbing premise of the books and the fact that they were written for an adolescent audience but I found the books very interesting and found myself rooting for the protagonist. I'm currently reading the final book in the series and am curious to see how the series will end.
As you can see, I read across the board from memoirs, to novels, to mysteries to self-help, but I have a penchant for memoirs. In 2011, I plan to read more books on investing and entrepreneurship, but I've gotten through a lot of 'must reads' on my book list in 2010. I recently heard a statistic that I can't exactly recall about the dismal reading rates of Americans which amazes me because I see so many people in D.C. toting around books and e-readers on public transportation. But I personally find that reading for fun (and information) makes me feel more well-rounded and makes for great conversation with friends, associates and colleagues. So, read up!

What were your favorite books of 2010?

Monday, November 22, 2010

Being Thankful


Thanksgiving is only a couple days away (where did this year go…)! In an effort to bring the year to a close on a positive note, I’d like to outline the things I’m grateful for this Thanksgiving:

  • My health.
  • My loving family and supportive friends.
  • Being gainfully employed with great benefits.
  • Slowly building my savings and retirement funds.
  • Being weeks from completing my Master’s degree (whoop!).
  • Living in a part of the city that I love in an awesome apartment.
  • Being relatively young and having fun milestones to look forward to personally and professionally.
  • Having been able to afford to travel for pleasure this year.
  • I could go on, but I'll stop here.
I don’t often take the time to think about how many things I really have to be thankful for, so I plan to do this more often in the future. In general, I think it’s so easy to get caught up with focusing on what we don’t have and goals that haven't met instead of focusing on the considerable abundance many of us have in our lives. Life isn't perfect and things don't always work out as planned, but that's what makes it interesting!

What are you thankful for this Thanksgiving?

Tuesday, September 21, 2010

Happy Dance for Annual Salary Increases

I recently received my annual salary increase which should be reflected in my next paycheck. I accordingly increased my retirement contribution to my 403b so I will still be meet the minimum threshold to be eligible to receive a 'match' contribution from my company. I really try not to increase my 'lifestyle expenditures' when I receive salary increases and allocate the money to different pots and pretend like the increase doesn't exist. I'm not the only one that needs the incentive of these little mental tricks, right?

My increase was actually reflected a bit late this year, so I will receive a small windfall from retroactive pay from my new salary. This small windfall will go straight to my travel fund which I’m still in the process of beefing up for my fall travel plans. This small windfall and annual increase called for a brief happy dance which I did during the day yesterday when no one was watching. Hey, I need to work exercise into my daily routine anyway and every little bit counts right? : )

Friday, September 3, 2010

September 2010 Goals

It's about time I get back into setting my monthly goals, so here are my goals for the month of September:
  1. Apply for December 2010 graduation. I'm in the final stretch of graduate school, so I have to talk to my academic advisor and fill out the paper work to apply for fall graduation. It's amazing how fast two years fly by!
  2. Save for fall travel 'spending money.' Though I paid for both trips I plan to take this fall (a 7 day cruise and a long weekend in Paris), I still have to set aside more money in my travel fund for spending money. I plan for most of my travel money to be spent on food. I truly have enough stuff; I can do without souvenirs, my main souvenirs will be photos : )
  3. Order all of my FICO scores. I did check my credit report earlier this month via Annual Credit Report , but I haven't checked all of my credit scores this year. I will order them all and take a look at them.
  4. Borrow some French language software from the library and start practicing. I'd love to purchase Rosetta Stone, but since that doesn't fit in my budget, I'll have to settle for borrowing some language software from my local library. It's been a long term goal to learn to speak French conversationally for a while and I've forgotten most of the French I learned to fulfill my foreign language requirement in college, so language software from the library will have to do for now. Once I feel more comfortable with basic conversation, I'll start attending French conversation Meet-ups. I never had the nerve to attend language Meet-ups in the past, but I plan to change that in the near-future!
  5. Start exercising 3 times a week (again). Some how exercising has fallen by the wayside for the past few weeks (okay, months), so it's time to get back on track again. I'll do the 30 Day Shred though I don't think I'll to do it for 30 consecutive days, I'll alternate with Pilates and Yoga stretching. I'd also like to take at least drop-in dance class; one of the advantages of living in a city like D.C. is that there are quite a few dance studios.
  6. Henna my hair. Henna which is traditionally used in Pakistan and other parts of the world to decorate skin is also used by many women as a natural dye and conditioning treatment. It coats (doesn't penetrate) your hair in red which will show up in varying degrees depending on your hair color and how long you leave on the henna. I can't tell any difference in my hair color which is very dark, but it was a great conditioning treatment! It's a little messy/time consuming, but I plan to do a henna treatment once a month. I have to order the henna (I used this brand the last time) and set aside a Sunday to do it.
  7. Take clothes donation to Goodwill. I sorted through my clothes earlier this summer and set aside a bag of items I no longer need to take to Goodwill. I'm tired of looking at that bag in my hallway, so it has to go!

Happy Friday folks!

Friday, August 6, 2010

Non-Summer Travel Blues

I have done very little travel this summer. For the past few summers, I have gone on a few family weekend trips and at least one trip with my friends. I didn't realize how conditioned I was to think that summer means that it is time to travel! As I've mentioned previously, I do actually have a few travel plans for the fall and elected to pool my money toward those plans and turned down most of the travel plans offered up to me by both friends and family over the past few months. I even slowed down on visits to my hometown; it has been the norm for me to go home more frequently during the summer months since college. I didn't mind the idea of no summer travel at the beginining of the summer, but as the summer flies by (alarmingly fast might I add), I kind of wish I had some travel plans between now and the official end of the summer to look forward to. I might try to squeeze in a day trip somewhere close but that will be the extend of my travel until the fall. I love taking advantage of things going on locally, but personally, there is nothing like a nice trip (outside of the immediate area where you live) to look foward to.


Does anybody else that opted out of traveling this summer feel the non-travel blues as well?

Saturday, July 24, 2010

My First Sewing Project


I've had the goal of learning to sew for years (literally!) and decided that 2010 is the year that I start working toward this goal. I made the shorts above as a project at a beginners sewing workshop I took here. The 2-hour class cost $40 plus the cost of fabric (which they sold at the store) and included usage of a sewing machine and materials like thread, measuring tape and scissors. At the end of the class you have a project completed. I opted to make shorts instead of pants as the instructor initially suggested.

I definitely plan to go back and take a few more classes to master the basics and am toying with the idea of eventually taking some classes in knitting as well. The imperfections may not be apparent from the photo above, but I'll definitely need to work on mastering sewing on a machine in a straight line : ) Threading a bobbin without help will also take a little practice.

So what is the value in spending my money on things like sewing classes when I have no aspirations of becoming a Project Runway contestant?

  • As a creative person, it's worth it for my personal happiness level to learn skills that are both useful and creative. Sewing fits those requirements.
  • I hope to master sewing well enough to do most of my clothing alterations and even make some basic items for myself like skirts. This would save me a lot of money over time because as a petite lady, a lot of my pants and other clothing require alteration before wear. As a result of the extra money required to purchase pants, I rarely buy them these days.
  • I like the idea of giving more hand-made gifts. Hand-made gifts can also be cost-effective in many cases if the materials required to make the gift are inexpensive. For instance, I could make a baby blanket for the next family member or friend that is expecting.

Learning to sew proficiently won't happen overnight, but I feel positive that it's an attainable goal with some instruction and a little practice. I plan to track how much money I spend on learning to sew and on the cost of materials during and after the 'learning' process.

Friday, July 16, 2010

Infograph: Credit Card Statement Changes

I'm sure many people are aware that as of July 1, your credit card statement has to meet specific formatting guidelines laid out by the Federal Reserve. These requirements are part of a larger set of rules put into place by the Fed in 2008. Five Cent Nickel created this infograph to illustrate the changes that I'd like to share.


While the new reporting requirements for credit cards statements will be helpful to some people, I don't suggest carrying credit card balances in the first place if you can, it's no fun at all paying them down, I speak from experience. It's only fun to the watch interest grow on investments and savings : )

Wednesday, July 14, 2010

Would you buy a property with a friend?

As I recently perused condo listings/real estate blogs and daydreamed about the day when I’ll be able to afford to become a homeowner, one particular listing caught my eye. This listing billed a 2-bedroom condo in my city that is up for sale as "perfect" for friends that want to purchase a home together. This listing made me pause and think about whether I would consider purchasing a property with a friend if I end up becoming a homeowner before I marry, which could feasibly happen since I am not married yet. Purchasing property with friends/significant others is not unheard of, but honestly, it’s just not something I ever considered. I’m aware that many 20-somethings live with their significant other’s or friends (and sometimes both!) and some also choose to purchase property with them.

But in my opinion from the outside looking in since I’m not actually in this situation, purchasing a property with someone other than a spouse brings up many considerations. I don't feel that I can effectively talk about issues around cohabitation, but other personal finance bloggers have succinctly explained this issues on the 'Interwebs.' I’ve never actually had a ‘falling out’ with a friend since adulthood, but I’d be wary of making such a huge financial decision with a friend or group of friends. What happens if your co-owner/best friend becomes your ‘frenemy’? I don’t think I’ve ever actually used the word “frenemy” in a sentence. I’ve clearly been watching shows like The City too much lately…Here are a few positive and negative considerations that could come into play when purchasing a property with friends:

Positive considerations
  • Pooled resources can translate to a larger down payment than one person could afford on their own in most cases.
  • You have the ability to customize a home more than you can with a rental (you can't even't paint your walls in some rentals).
  • You are building equity in a home instead of paying out rent.
  • If you happen to be an animal lover, you can have pets in a home if your co-owners agree to the pet.
  • Shared housing whether you are a renter or homeowner generally translates into lower housing costs.
  • Some legal concerns that co-owners going into the situation have can be addressed in some type of agreement or contract to prevent issues down the line. The agreement could addresses issues like how to handle transference of ownership among other key issues.

Negative considerations

  • All co-owners may not have credit ratings in a range good enough to get the best possible interest rate for a home loan.
  • Liquidating property when one or more of the co-owners is ready to move may be difficult if all parties aren’t ready to move at the same time.
  • Co-owners may have differing opinions on how much money should be spent on insurance or budgeting for unexpected expenses.
  • Issues could arise if all co-owners can’t agree on what their ‘pet policy’ will be.
  • Typical ‘roommate issues’ such as miscommunication around cleaning, maintenance, housework can arise.
  • Potential problems could arise if one of the owners is unable to pay mortgage due to issues such as loss of employment.
  • Coming to a consensus on issues like home improvements and décor may not be easy.

Sharing homeownership with a friend (or more than one) is not something I would discount completely, but it would take a lot of consideration before I would agree to it. I'd personally rather wait until I am in the financial position to purchase a property on my own or with my future spouse.

But what do you think, would you buy a property with a friend?

Thursday, July 8, 2010

Ways to Live Big on Small Earnings During the Summer Months


Guest Post by Jena Ellis


It's summer time and having fun should be easy and inexpensive. This statement can even be true for those who are looking to live big on small earnings. After all, summer fun shouldn't be all about spending piles of money, doggedly monitoring your bank account, or breaking a sweat over whether or not you can afford a jaunt to the beach. This season, you and your wallet can relax if you adhere to a few simple tips for maximizing every last cent of your allotted spending money.


Use Coupons. Do not underestimate the savings that coupons can offer. Clipping coupons from the Sunday paper and weekly circular can seem like a waste of time – after all, most coupons only offer savings of several cents to a dollar – but if you find coupons for all of your basic purchases, you can easily add those cents and dollars up to save a total of $10 to $20 on your groceries and department store purchases. This can make shopping for a backyard barbeque much more affordable. The savings doesn't have to stop with just brick-and-mortar stores. Online retailers often offer promotional codes that can range in deals from additional percentages off the total cost to free shipping. You can find numerous online promotional codes for your favorite online retailers at sites like FatWallet.com and RetailMeNot.com.


Explore Your Community. When you're itching to break away from the norm and try something new, check your local newspaper or community lifestyle website to find out what free or low cost festivals, shows, and other events are going on in and around your city. You can even make a fun "staycation" activity out of it! You may find yourself pleasantly surprised at all of the interesting events that occur nearly every weekend in bustling towns, especially during the summer. Visit your city's museums on designated free admissions days. Take a trip to the farmer's market to browse and try free samples of local fare. Stop by cultural festivals for free shows and good eats. You can live big while spending less by exploring all that your city has to offer, making staying in town for the summer much more exciting.


Entertain at Home. If you're looking for an affordable way to host a big summer bash, consider hosting a potluck party either in your own backyard or in a public place like the community pool or park. If you are hosting your party in a public area, you can easily have more fun and gain even more potluck dishes by inviting the entire community to come out and soak up the sun with you. A potluck party is great for stretching your dollar because your guests will each bring a dish to share so that you won't have to cook for the entire group. The best part is, you'll still end up with plenty of food, laughs, and memories to go around. And isn't that what living big in the summer time is all about?

This guest post was contributed by Jena Ellis, who writes on the topics of Online Certificate Programs. She welcomes your questions and comments at: jena.ellis20@gmail.com.


Monday, July 5, 2010

My Thoughts on The Power to Prosper By Michelle Singletary


During the month of June, I borrowed a book from the library called The Power to Prosper: 21 Days to Financial Freedom by Washington Post personal finance columnist, Michelle Singletary. Although I have read her column in the Washington Post for the past several years and have actually heard her speak in person, I've never actually read any of her books. I decided that I would remedy that in 2010 and decided to read her most recent book.

While most (if not all) of the information presented in The Power to Prosper was not new to me, I found the book helpful in reinforcing personal finance topics that I have learned about over the last few years. The book presented a lot of information on the benefits of doing a financial fast to focus on financial goals. Personal finance fasting the Michelle Singletary way can help people that struggle with overspending, having a less materialistic lifestyle, budgeting and paying down debt. The Power to Prosper was presented for a Christian audience. This did not bother me at all, but if you aren't interested in approaching your finances from a spiritual basis (Biblical to be more specific), this book is probably not the book for you.

The Power to Prosper gives you day-by-day instructions on implementing a 21-day financial fast. I also liked the real stories interwoven into each chapter related to the topic of that chapter. To be completely honest, I did not actually fully implement the financial fast while I was reading this book because I made prior commitments with friends and family that called for spending money that I did not want to break (birthdays, baby showers, get-togethers). But during the month that I read The Power to Prosper, I did suspend extraneous shopping (clothing) and applied a recent windfall (student loan refund check) to debt repayment.

After reading the book, I definitely feel inspired to check out it out again in the fall and fully implement a 21 day financial fast, but it would take some preparation such as telling my friends/family/colleagues that during that time period, I won't be accepting invitations/participating in activities that would cost me money. Financial fasting is very achievable, but may take some preparation. Just as people cut down on or limit food-intake to eliminate toxins from the body, fasting from spending is meant to get spending in check and could be useful even if you don't have debt, or are already saving for retirement, college educations for children, mortgages, etc. It's just a more stringent way to implement that internal dialogue that many of us go through when we spend money. I regularly ask myself questions like "Do I really need that?" or "Is this item a need or a want?" when I shop. The Power to Prosper did remind me of the sacrifice that it takes to meet financial goals and encourage me to keep working toward them.

If you are already on track to meet certain money-related goals (budgeting, paying down debt, saving for retirement, etc.), this is probably not the book for you. I definitely suggest this book. for anyone who is just starting to focus on their personal finances, or to someone that would like spiritual inspiration to help them manage their finances.

Wednesday, June 23, 2010

Random Personal Financial Thoughts

I've been MIA for most of the month on this blog due to a busy schedule, but personal financial concerns are still (let's be honest ALWAYS) on my mind:

  • I’m thinking about cancelling my gym membership because I use it so sporadically. I do enjoy the amenities of a gym, but I can find alternative ways to exercise for less money. For example, I recently discovered that there is a public swimming pool walking distance from where I live that is free for DC residents! That $45 per month could be padding my emergency fund instead of paying for my (infrequently used) gym membership.
  • I plan on making July a low-spend month by limiting my travel and extraneous spending. I’ll also try to limit my restaurant/take-out meals and take advantage of free events that are going on in the city instead.
  • I purchased one baby shower gift this month and have to purchase two more baby shower gifts within the next few days. Buying baby shower gifts a few times a year for close friends and family members comes with the territory of being a 20-something female, but they aren’t usually clustered so closely to the same time period for me. I need to replenish my gift fund for unexpected gift giving so I’m better prepared.
  • For me personally, picking up a new book for my Metro commute is just as fun as buying something new. The D.C. Public Library is such a great resource! As soon as I have free time, I'll pick up some French language software, since I’m still saving up for Rosetta Stone.
  • It’s time to start thinking about an aggressive repayment plan for my student loans since I will enter my last semester of grad school in the fall and my in-school loan deferment will end. I’m thinking of using an approximation of the ‘debt snow ball method’ and paying them off from smallest balance to largest balance.
  • My Roth IRA and 403 B accounts seem to be increasing so slowly. Meeting my goal of having as much money in my retirement accounts as I make on my (current) annual salary by age 30 seems kind of lofty at the moment. But I believe it’s still attainable.


What random personal financial thoughts do you have on your mind today?

Saturday, May 22, 2010

Hesitations in paying for certain things

Attending a recent club party made me realize that at the 'advanced' age of 26, the idea of going to a (dance) club doesn't make me cringe yet, but the idea of paying a lot for one does. I honestly love (almost) any occasion that causes for me to dress up, but paying a lot to 'party' sucks all of the fun out of it for me. My behavior is very different from what I exhibited during and immediately after I graduated from college. Washington, DC, the city I've lived in since graduating is a 'college' town and several of the notable dance clubs here throw huge parties that some celebrities and notable sports athletes attend when they are in town. But attending these parties comes at a steep (to me) price unless you are 'connected' with someone affiliated with the club, are on someone's guest list or take advantage of the incentive many clubs offer of ladies to enter for free or cheaper before a certain time (usually 11:00 p.m.). I think guys get usually get a cheaper price as well, but I'm not sure if it's free.

During my college years I remember spending as much as $40 to enter a club during a special occasions like homecoming season amongst local colleges or graduation season. That entrance fee doesn't even cover your drinks. The fact that I always drink minimal alcohol when I socialize probably meant that I spent less than most but that's still alot! I enjoyed that time in my life, and don't really regret spending that money, because it came with the experience of being that age. But now that I am my mid-twenties and not my early twenties, my priorities have changed and I'm not interested in paying that much money for a club. I'd rather save it or if I spend it, I'd rather have a nice meal, go to a concert or even get a manicure/pedicure than pay for a club. I think most of my friends that went to my university would agree but you couldn't tell us going into whatever parties we paid all of that money to attend wasn't 'important' back then.

Is there anything you hesitant (or unwilling) to pay for as you get older?

Monday, May 17, 2010

Summer Travel Plans

I don't plan to do much traveling this summer. I'm planning to take two classes this summer for grad school and am considering taking another non-grad school related class that I think might give me a few useful skills I can use on my job. Because I intend to be pretty busy, my traveling will be relegated to weekends. Here are my tentative travel plans:
  1. Visit family members. I've already purchased airfare to visit my Dad who lives in another state and may also go to at least one family reunion in a near-by city.
  2. Go to a (relatively) near-by beach. I'm hoping to take at least one trip to a near-by beach either in Delaware, Virginia or New Jersey.
  3. Day trip to NYC to visit some musuems or other sightseeing. I've already been to NYC a few times this year to see an excellent show and do some shopping/thrifting, but I'd like to take at least one day-trip via Megabus to see some cultural sights and museums that I have never seen before like The Met and MOMA.
  4. 'Staycation'. I'd like to take advantage of some of the great things going on in my city this summer as well and deviate from my usual routine. I still have to do some research on what I'd do on this staycation.

I still have to set an exact amount I plan to spend on travel this summer, but I don't plan to spend as much as I have during past summers because they included more air travel and hotel stays.

What are your summer travel plans?

Friday, May 14, 2010

Summer Barbeque Options for Vegetarians

Though the weather has been finicky recently, summer is right around the corner and I am looking forward to attending barbeques once the weather warms up for good in the Mid-Atlantic region. But I don’t want my recent commitment to vegetarianism to put a crimp on my summer barbeque food options. I also don’t want to rely too heavily on bread to fill up which wouldn’t be friendly to my waistline in excess. Here are a few recipe items I’ve found that are also relatively inexpensive:


Other good vegetarian friendly options I plan to try include:
  • Roasted or Grilled Vegetables
  • Fruit Salad
  • Mixed Green Salad
  • Grilled Corn
  • Gazpacho Soup (with Mango or Watermelon)

Do you have any vegetarian-friendly summer dishes you’d like to try this year?

Wednesday, May 12, 2010

Interesting Personal Finance Articles

Here are few recent news articles that I found interesting:

Networth Obsession - I like to see progress in the positive direction on my networth like anyone else, but I don't see the point in getting too 'caught' up in the numbers.

Thinking Outside Rails and Runways, and Taking the Bus - As a frequent Megabus rider, I'm not surprised that bus-riding is catching on among younger (and older) adults. The lower cost of bus travel vs. Amtrak makes traveling along the East coast much easier for me personally.

Credit or Debit? Which Card You Should Use, and When - This is a question I often ask myself when making larger purchases or booking hotel rooms.

Generation Y's Steep Financial Hurdles: Huge Debt, No Savings - Yet another 'downer' article about my generation. This article was even more motivation for me to get my financial act together. There are many Generation Y'ers out there that are fiscally responsible. I chat with quite a few of them on the internet and have met some of them at the two blogger happy hours I've gone to in DC. I hope to meet more like-minded people my age in the future.

Exploiting the New Student-Loan Rules - I don't think I need to take advantage of this option at this time, but it's good to know it exists.

Have any recent news stories or (blog posts) caught your eye recently

Monday, May 10, 2010

Cutting out little splurges to reach financial goals

I have never been the type of person to spend a large amount of money on any item at one time. I usually have little splurges that (psychologically) make me feel less guilty about spending money. But as most people realize that track their money, those little splurges can add up to a lot of money over time. I’ve spent most of 2010 so far burying my head in the sand about my little splurges. I'm sure many people have heard of David Bach's Latte Factor. But lately, I’ve been trying to make a conscious effort to cut out those little splurges and only spend money on planned expenses but I have to admit it’s hard for me. Small treats like a latte from Starbucks or a new lip gloss from CVS or an album I’ve been contemplating downloading off of iTunes will have to stay in their respective stores where they belong. I also need to stay out of my favorite big box retailers altogether for a while to avoid temptation. After looking at my calendar in dismay and seeing that the year is half way over motivated me to be a little more cautious in my spending so I can really see some progress at the end of the year with my financial goals. I’m not on a spending fast, but am doing the diet equivalent of ‘stepping away from the table before over-indulging.’ I'm going to put any 'leftover' money I have after my expenses into debt repayment, because that is my focus right now. Though I don’t plan on taking up antisocial behavior to save money, I will try to spend as little money as possible while partaking in any activities. I think that summer approaching actually works in my favor of my efforts to spend less. I do live in DC after-all, there are plenty of low-cost things to do here, if I look hard enough.